The fed cattle market slipped narrowly last week as larger market-ready supplies in the North pressured the most actively traded cash region of Nebraska, Iowa, and South Dakota. Values in that region resulted in the $219 to $220/cwt. range while much shorter supplies down south held the Texas market to $226/cwt.
As a result of packing disruptions in Kansas two weeks ago, there was a dramatic reduction in throughput. This was followed by last week’s recovery of 548,000 head. The weekly average across the two-week period of 516,000 head was 47,000 head per week below a year ago.
Weekly carcass cutout values are holding their own and in summary, were slightly higher last week across grades. Reportedly, some boxed beef orders were unfulfilled, in part because of the Kansas plant disruptions . Fed cattle throughput in the past four weeks has been small enough to hold cutout values within their current range. Widening price spreads, based on quality grade and branded supply availability, have been a key market component in the recent weeks.
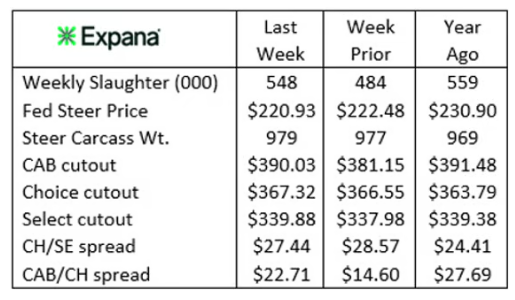
The rib primal is trading at new record-highs as smaller ribeye piece counts are only partically supported by larger individual cut weights. Both chuck and round primals were also pricing higher in last week’s reports, while the loin primal averaged out to a sideways trend. Short loin prices are slightly lower than a year ago at this time. But once again in the fourth quarter, it’s anticipated that end-users will soon turn to loins as an alternative to the record-high ribeyes.
Steer carcass weights continued their upward march with a 2 lb. increase in the latest report. Expectations remain intact for the fall carcass weight highs to surpass those of a year ago with recent weights 10 lb. heavier than last year. Last week’s heavy rain totals across much of the nation’s feeding belt could lend to less rapid feedlot gains and a slowing of resulting carcass weight increases toward the annual high.
Price Spreads Widen, Robust Quality
The boxed beef market posted massive year-over-year increases beginning in April 2025. The remainder of the 2025 market featured an average 19.9% increase in the USDA Comprehensive Cutout (all grades, all delivery periods). The pattern largely remained intact as the first five months of 2026 recorded a 14.8% annual price jump for the period.
Continued increases of this magnitude were logically unsustainable as the market featured a cooling price pattern over the summer. Since June the Comprehensive Cutout recorded lower prices than a year ago in 10 out of 18 weeks. Yet the average for the period was just 0.4% lower than the 2025 values for the period. Keeping this in context, the June-September average prices represent a 21.3% two-year increase.
Despite the end of this inflationary run, signs of seasonal normality have emerged in the boxed beef market. This reference is specific to widening carcass quality price spreads, posting an impressive recovery from uncharacteristically narrow spreads during the first half of the year. USDA Prime carcasses were trending to a spring record-high 17% of steer/heifer carcasses and USDA Select was at a record-low 7.7%. This pushed price relationships into uncharted narrow territory for the period.
The quality-rich product mix seasonally subsided into August with the Prime grade dipping into 12% territory, building back to 14.8% of the total in the latest report. Driven primarily by Prime share increases, combined Choice and Prime grades are three percentage points higher than a year ago, a theme that summarizes the entire grade landscape year to date.
With fed cattle harvest running more than 7% below a year ago, total product supply is an important consideration. Calculated raw Prime carcass tonnage has been 25% higher than a year ago, (head count up 17%) while Choice tonnage has been 4% lower. Added carcass weights have meanwhile cut the deficit nearly in half.
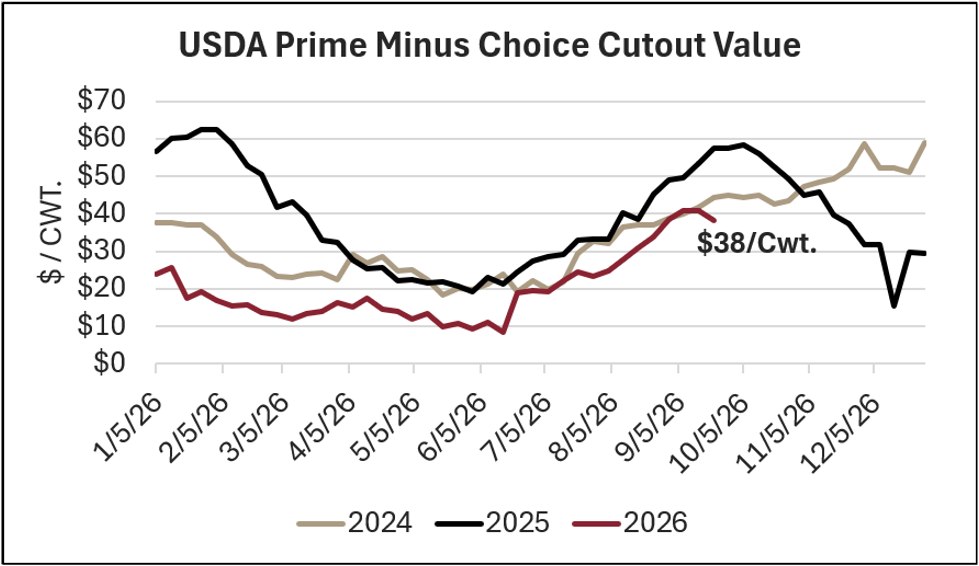
Against this backdrop, the Prime cutout premium to Choice has increased from the summer low of $8.54/cwt. to it’s most recent $38.34/cwt. Still $19/cwt. smaller than a year ago, it’s an impressive rally on a historically burgeoning Prime supply. While USDA Select customers are getting increasingly harder to find, the Choice-Select spread has improved from last spring’s “near zero” values to it’s most recent $21.96/cwt. on USDA’s report, $2.74/cwt. higher than a year ago at this time. (Expana’s simple average is $27.44/cwt.)
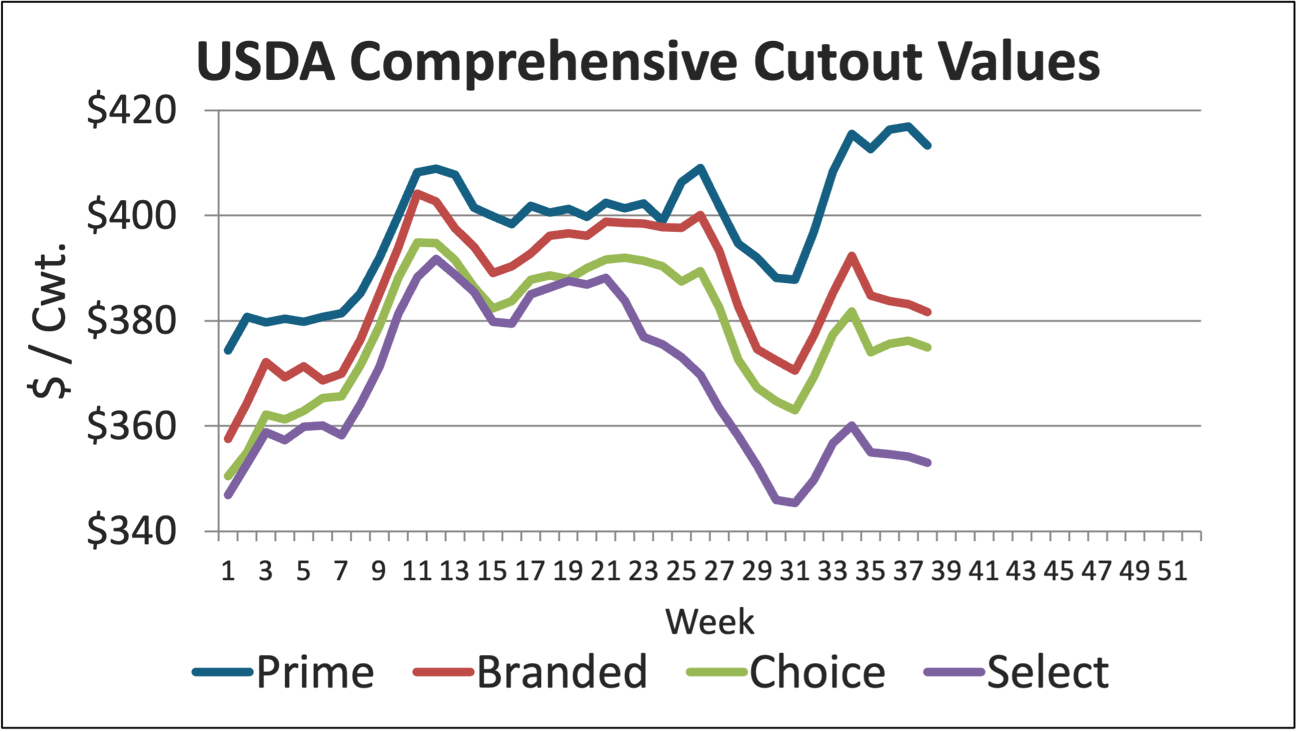
Traditional Certified Angus Beef ® brand carcasses were $22.77/cwt. premium to Choice in last week’s market. This is the largest premium since January, roughly $5/cwt. larger than the year-to-date average. Brand carcass supplies (combined Premium Choice and Prime) in the past six weeks are down 9% on a year ago, a direct result of smaller weekly harvest head counts. Supply growth is noted in the brand’s Prime brand extension, similar to the overall USDA Prime carcass complex, while traditional CAB carcasses are currently reduced.
Quality price spreads, while not record-wide, are behaving in a seasonally appropriate manner at levels, incentivizing the supply chain to pursue the course. This is evident in the larger grid-marketing by feedlots last week and should further encourage such sales in the near term. That is quite the opposite view rendered by last spring’s year-over-year surge in cutout values coupled with a shockingly rich quality-grade mix.