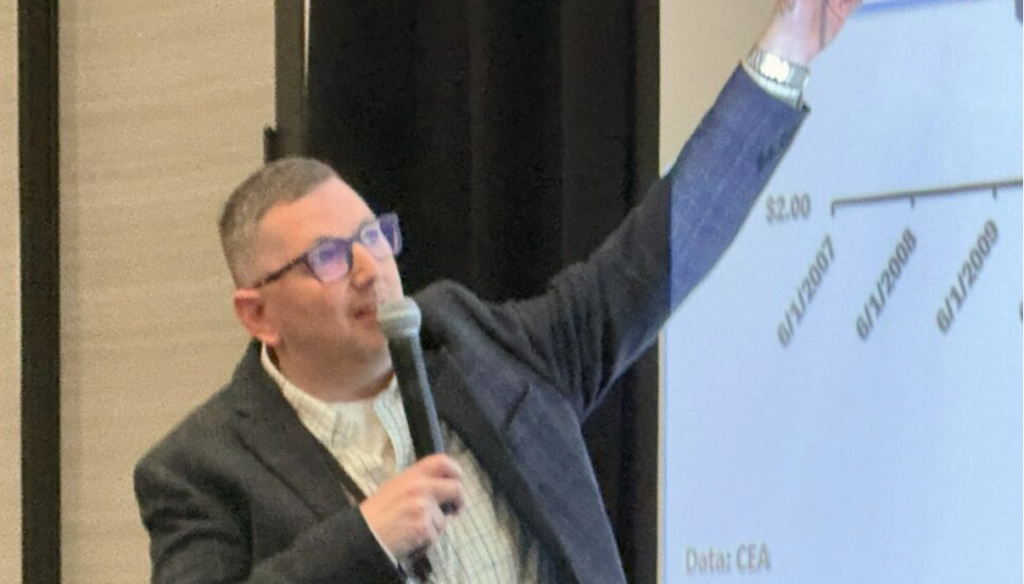
Volatile crop markets and planting uncertainty are creating a challenging backdrop for Oklahoma producers as fall fieldwork gets underway. After starting the week on solid ground, commodity markets gave back their gains and then some, with hard red winter wheat contracts dropping roughly 30 cents from Monday’s highs. Farm Director KC Sheperd recently sat down with Oklahoma State University crop marketing specialist Todd Hubbs to break down the global pressures, weather patterns, and marketing decisions affecting winter wheat, soybeans, and feed grains.
Hubbs pointed out that while day-to-day market moves have been dictated by trade speculation, energy market noise, and broad geopolitical risk-off sentiment, the core fundamentals for wheat have not undergone a dramatic shift. The primary issue remains getting money back into commodities while trade flow faces headwinds.
Winter Wheat Planting and Weather Concerns
Oklahoma producers are looking at fields and evaluating soil moisture as the winter wheat planting window opens. Although sporadic showers have crossed parts of the state, many growers remain hesitant to dust the crop into dry ground.
Hubbs noted that while early USDA planting pace numbers reflect an average start, progress could easily fall behind if widespread moisture does not materialize. Central and northeastern Oklahoma are in particular need of significant rainfall. Producers are also keeping a close watch on weather outlooks featuring a Super El Niño pattern, which historically tends to bring wetter winters to the Southern Plains and could assist in crop establishment if rain arrives in time.
Small Grains, Black Sea Bottlenecks, and Export Realities
Looking ahead to the USDA Small Grains Summary, Hubbs said he does not anticipate major revisions for hard red winter wheat production, expecting figures to remain close to current estimates. While final spring wheat numbers will provide clarification following rumors of potential quality issues, the broader issue for the wheat sector remains sluggish movement.
Recent export sales data showed the U.S. running well behind its historical pace. Although a smaller overall domestic crop naturally limits total export volumes, current U.S. wheat prices remain elevated compared to the rest of the world, dampening international demand. Core buyers such as Japan and Mexico continue to make small, routine purchases, but broader demand expansion is quiet.
Globally, logistics across the Black Sea remain severely constrained. Russia has declared an emergency across key wheat-producing regions due to logistical backlogs, and military actions around Black Sea and Danube River ports have driven delays. Hubbs noted that vessels face wait times two to three times longer than normal along Danube routes, and alternative shipping through Baltic or inland corridors remains slow. Furthermore, sluggish planting progress in the Black Sea region suggests potential acreage reductions for their upcoming crop, an indicator that could eventually lend support to new-crop wheat values.
Soybean Strategies and South American Weather Risks
Turning to soybeans, Hubbs discussed pricing strategies for growers holding unpriced new-crop supplies. With contract prices hovering above $13 per bushel, Hubbs characterized the current market as a respectable pricing opportunity for producers needing cash flow.
While domestic crush demand remains steady, a soft August crush report points toward the USDA trimming old-crop crush numbers by roughly 10 million bushels, alongside modest reductions in soybean oil use for biofuels. However, finalized biofuel policies and stable domestic demand should keep crush levels supported moving forward.
For growers considering carrying soybeans into the new calendar year, weather conditions in South America represent a notable wildcard. A Super El Niño often brings dry patterns to northern Brazil, a region that has significantly expanded its soybean acreage over the past decade. If dry weather shortens Brazil’s crop, the market could see price rallies later in the winter, though Hubbs cautioned that confirmation of any crop shortfall would likely not arrive until January or February.
Grain Stocks and Feed Demand
The conversation wrapped up with expectations for the upcoming Grain Stocks report. Hubbs highlighted corn stocks as the primary area to monitor, noting that corn balance sheets rely heavily on the residual feed category. Because feed and residual demand is calculated from quarterly stocks rather than measured directly, any unexpected buildup in corn supplies could lead to downward adjustments in total consumption. While Hubbs does not anticipate a dramatic shock in the report, grain stocks will serve as a key checkpoint for corn and feed grain balances heading deeper into the harvest season.