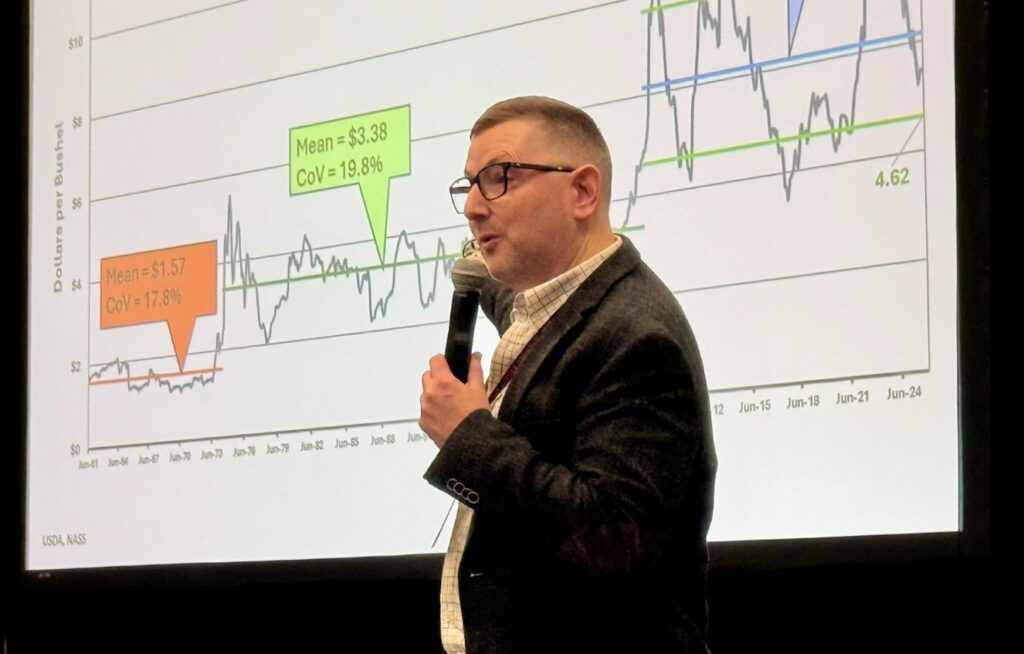
Developing resilient grain marketing strategies is top of mind for agricultural producers as post-WASDE market dynamics, weather disruptions, and global trade uncertainties collide. Oklahoma State University Crop Marketing Specialist Dr. Todd Hubbs sat down with Farm Director KC Sheperd to evaluate the commodity landscape following the latest USDA World Agricultural Supply and Demand Estimates (WASDE) report, outlining practical risk management steps for Oklahoma growers facing volatile cash and futures markets.
Hard Red Winter Wheat Slips as Export Sluggishness Catches Up
December Hard Red Winter (HRW) wheat futures broke below the psychological $8.00 mark, pulling back into the low $7.90 range and erasing the late-August rally. Dr. Hubbs observed that while technical selling and profit-taking accelerated the post-report slide, fundamental factors justified the weakness.
The USDA lowered HRW export projections by 15 million bushels, reflecting a sluggish pace that has persisted for weeks. Meanwhile, world ending stocks edged higher both with and without China’s reserves factored in. Modest increases in Canadian ending carryover and reduced export flow from the Black Sea—which keeps unsold grain in local stockpiles—further weighed on sentiment.
Looking forward, Hubbs noted that the Small Grains Annual Summary released at the end of September will deliver final winter wheat production numbers and spring wheat yields, serving as the next major fundamental anchor. While rumors have surfaced regarding potential agreements between Russia and Ukraine, Hubbs called them far-fetched, cautioning that persistent Black Sea uncertainty will keep volatility elevated heading into the fall.
Corn Holds Stable on Solid Disappearance and Predictable Yields
In contrast to wheat, corn demonstrated resilience following the report. National average yield landed at 178.5 bushels per acre, aligning closely with private models and pre-report expectations.
Strong domestic demand across ethanol production alongside steady export commitments continues to provide a dependable price floor. Hubbs does not anticipate substantial yield revisions moving between September and the final annual figures, as historical adjustments rarely exceed a bushel or two per acre unless weather turns catastrophic. Consequently, corn values are expected to trade in a defined sideways range until fresh demand signals emerge.
Soybeans and Meal Charge Ahead Amid Wet Harvest Conditions
Soybeans pulled back modestly after a strong early run, but soybean meal surfaced as a major bright spot across the oilseed complex.
August crush rates came in below market expectations, indicating that future USDA projections could trim domestic crush by approximately 10 million bushels. However, the underlying meal demand remains strong. Prolonged excessive moisture across significant portions of the Corn Belt has delayed early bean harvesting, creating near-term supply tightness and supporting cash basis.
Longer-term, Hubbs pointed out that ongoing purchases by China and favorable domestic biofuel mandates give soybeans strong support to stay above the $13.00 mark.
Global Headwinds: El Niño Risks, China Trade Talks, and Surging Fuel Costs
Several macro variables carry the potential to disrupt grain and oilseed fundamentals heading into late 2026 and early 2027:
- El Niño Climate Patterns: Weather models indicate a high probability of an El Niño peak between January and March. Such a shift could create dry conditions across northern Brazil and critical safrinha corn zones, as well as portions of Brazil’s soybean belt. Hubbs warned that if South American production suffers, it could trigger an explosive upside rally across the global grain and oilseed complex.
- Trade Diplomacy: Looming high-level meetings between President Trump and Chinese President Xi Jinping could provide formal commitments on Chinese commodity purchases, particularly for the anticipated 25-million-ton soybean program and potential expanded buying of U.S. milo.
- Refining Constraints and Skyrocketing Diesel: Diesel prices hovering near or above $6.00 per gallon present a major operational threat. Refining limitations and escalating geopolitical tensions in the Persian Gulf and around Iran continue to inflate global ocean freight rates, inland trucking, and barge logistics, pushing local basis wider and directly squeezing producer net returns.
Managing Oklahoma Risk: Forward Pricing and Avoiding Unforced Marketing Errors
When addressing new-crop marketing decisions, Hubbs offered clear guidance for growers preparing to plant or finishing up seedings:
- Locking In Profitable Forward Bids: For growers looking at July new-crop HRW contracts near $8.00, typical Oklahoma basis levels of 60 to 70 cents under put local cash forward bids in the $7.30 to $7.40 range. Hubbs recommends forward pricing 10% to 15%, and up to 20%, provided producers have secured 75% to 85% crop insurance coverage to mitigate production shortfalls.
- Avoiding Commercial Carry Traps: Storing unpriced grain without an active carry strategy quickly erodes farm revenue. Commercial storage fees running 6 to 7 cents per bushel each month guarantee a net loss unless futures rally by an equal or greater margin.
- Hedging Discipline and Target Orders: Hubbs cautioned growers against overextending in speculative futures or options where sudden margin calls can create severe cash flow strain. Instead, he advised establishing firm target bids with local grain elevators or working alongside certified commodity advisors to capture spikes during brief market rallies rather than attempting to guess the absolute market top.